Startup financial statements often look very different from those of established businesses because young companies are still searching for repeatable growth, investing ahead of revenue, and operating with limited historical data. Investors can easily misread losses as failure, revenue growth as proof of success, or a large cash balance as financial strength without understanding what is happening underneath. A structured review of the numbers is therefore far more useful than relying on the confidence of a pitch deck or the excitement surrounding the product.
Why startup financials differ from those of mature companies
Early-stage startup financials should be read primarily as evidence of how the business model is developing, how efficiently capital is being converted into growth, and how much time the company has to prove its assumptions.
When evaluating a mature company, investors can often rely on years of revenue, profit, cash flow, margins, and operating history. Those numbers make it possible to identify trends and compare performance across multiple economic cycles.
A startup rarely provides the same level of certainty.
Revenue may have existed for only a few quarters. Expenses can rise dramatically as the company hires employees or develops its product. Profitability may intentionally be postponed while management invests in customer acquisition and expansion.
This means that conventional measures such as net income can be less informative when viewed in isolation.
A startup losing money is not automatically unhealthy. The important question is what the company receives in exchange for those losses.
If spending is producing strong customer growth, improving retention, increasing recurring revenue, and creating attractive unit economics, temporary losses may be consistent with a rational growth strategy.
If the company is burning similar amounts of cash while customer growth slows and retention deteriorates, the same losses tell a very different story.
Startup financial analysis is therefore heavily dependent on context.
Investors need to understand not only where money is going, but whether spending is generating evidence that the underlying business can eventually become sustainable.
The core statements you actually need to review
No single financial statement tells the complete story of a startup, so investors should connect reported revenue and expenses with cash movement, assets, liabilities, and operational metrics.
The most important areas to examine include:
- Income statement. Review revenue, cost of revenue, gross profit, operating expenses, and net income or loss. Pay attention to how quickly each category is changing and whether expenses are growing faster or slower than the underlying business.
- Balance sheet. Examine cash, receivables, debt, payables, deferred revenue, and other significant assets or liabilities. This provides a snapshot of the company’s financial position rather than simply its performance during a particular period.
- Cash flow statement. Follow how cash actually moves through operating, investing, and financing activities. A startup can report accounting revenue while still consuming substantial amounts of cash.
- Budget versus actual performance. Compare what management previously expected with what actually happened. Repeatedly missing forecasts can reveal problems with planning, sales assumptions, expense control, or management credibility.
- Supporting operating metrics. Depending on the business model, review metrics such as recurring revenue, customer retention, churn, customer acquisition cost, gross margin, average contract value, and customer concentration alongside the formal statements.
The relationship between these documents is often more informative than any individual number.
For example, rapid revenue growth looks attractive. But if receivables are increasing much faster than revenue, the company may be struggling to collect cash from customers.
Similarly, a healthy bank balance may initially appear reassuring. If the cash came from a recent financing round and the business is consuming it rapidly, the company may have a much shorter runway than the headline balance suggests.
Investors should therefore continually reconcile the story told by management with the story visible across the financial statements.
Key metrics that matter more than raw revenue at early stage
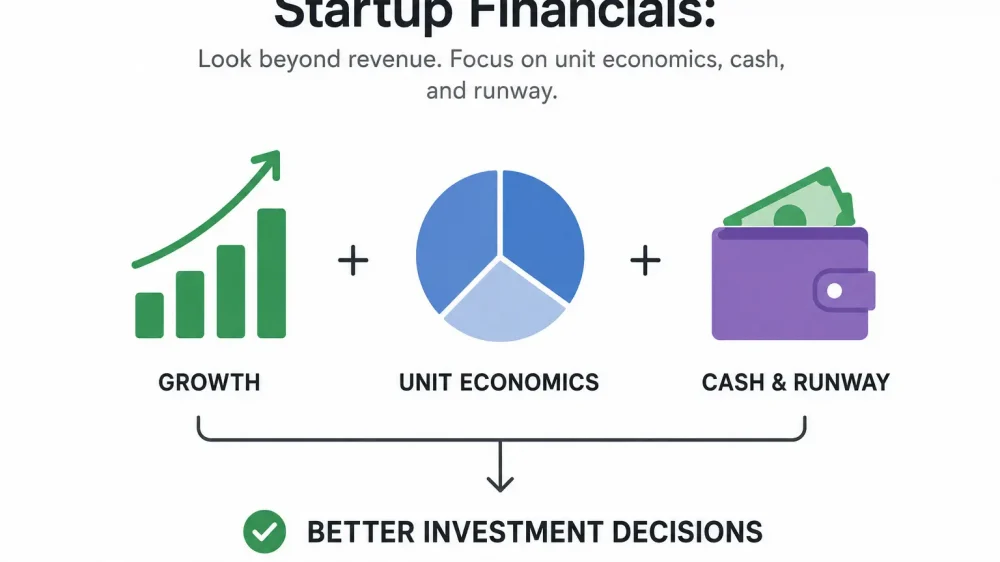
At an early-stage startup, the quality, durability, and efficiency of growth can be more informative than the absolute amount of revenue.
Revenue is obviously important, particularly once a company has started commercializing its product. But revenue alone says surprisingly little about the economics of the business.
Start with growth rate.
A company generating $2 million annually but growing quickly may present a very different opportunity from one generating $5 million with stagnant or declining growth. The appropriate interpretation depends on the market, stage, and business model.
Then examine gross margin. Revenue that costs almost as much to deliver as it generates provides less economic leverage than revenue with a healthy contribution after direct costs.
Retention is particularly important for recurring-revenue businesses. A company can acquire customers rapidly while simultaneously losing existing customers. Strong headline sales growth can temporarily hide this weakness.
Customer acquisition efficiency deserves similar attention. Ask how much the company spends to acquire a customer and how much economic value that relationship is expected to generate.
CAC and customer lifetime value can help with this analysis, but these metrics should not be accepted blindly. Small changes in assumptions about retention, gross margin, or customer behavior can dramatically change an estimated lifetime value.
Cash burn and runway are among the most practical metrics for an investor.
Net burn generally describes how much cash the company loses during a period after accounting for incoming cash. Runway estimates how long the company can continue operating at approximately that burn rate before requiring additional capital.
For example, a company with $3 million in available cash and a net burn of approximately $250,000 per month has roughly 12 months of runway if conditions remain unchanged.
That estimate is not a prediction. Hiring, revenue growth, cost reductions, debt payments, capital expenditures, and other changes can alter the result substantially.
Nevertheless, runway reveals something revenue alone cannot: how much time management has to reach the next important milestone.
How to work through a startup’s financials step by step
A practical financial review should move from revenue quality to unit economics, then to spending and cash runway, before testing whether management’s forecasts are supported by realistic assumptions.
A useful process consists of four stages:
- Understand where revenue actually comes from. Break revenue down by product, customer type, geography, contract structure, and recurring versus non-recurring sources where relevant. Look for customer concentration and determine whether reported growth comes from a broadening customer base or a small number of unusually large contracts.
- Examine the economics underneath that revenue. Review gross margin, retention, churn, acquisition costs, pricing, contract value, and other metrics appropriate to the business model. Determine whether growth becomes economically stronger or weaker as the company expands.
- Follow the cash. Identify the current cash balance, monthly or quarterly burn, major expense categories, debt obligations, and expected future commitments. Estimate runway under both management’s plan and a more conservative scenario.
- Stress-test the forecast. Identify the assumptions required for the company’s projections to work. Test what happens if sales take longer, customer acquisition becomes more expensive, hiring costs increase, margins improve more slowly, or the next funding round happens later than expected.
The final step is especially important because startup forecasts can create an illusion of precision.
A spreadsheet may contain detailed monthly projections extending several years into the future, but those numbers are only as reliable as the assumptions underneath them.
Instead of debating whether revenue will be exactly $12 million three years from now, identify what would have to happen for that result to become possible.
How many customers would the company need? What average contract value does the forecast assume? How many salespeople are required? How productive must each salesperson become? What churn rate is assumed? How much additional capital would be necessary?
Turning a forecast back into operational assumptions makes it much easier to evaluate its credibility.
Red flags that should make you pause before investing
The most important financial red flags are usually inconsistencies between the company’s growth narrative, its underlying economics, and the way management explains the numbers.
One warning sign is revenue growing while cash collection deteriorates.
Increasing accounts receivable may be perfectly normal for a growing company, particularly in enterprise businesses with longer payment terms. But receivables growing disproportionately fast can indicate collection problems or aggressive revenue recognition that deserves closer examination.
Customer concentration is another potential risk. A startup may appear to have significant revenue while depending heavily on one or two customers. Losing a single contract could then materially change the financial picture.
Watch gross margins as the business grows. Declining margins are not automatically problematic, but management should be able to explain why they are changing and whether the effect is temporary or structural.
Rapidly increasing burn without corresponding progress deserves attention as well. If spending doubles while revenue growth, customer retention, product development, or another key milestone barely improves, the company may not be converting additional capital into proportional value.
Repeated forecast misses are particularly informative.
Startups inevitably miss forecasts, and uncertainty is part of investing in young companies. The concern is not one inaccurate forecast. It is a pattern in which management consistently overestimates revenue, underestimates costs, or continually moves milestones without updating its assumptions.
Be cautious with unusually customized metrics too.
Startups sometimes present adjusted measures that exclude significant recurring costs or emphasize whichever numbers currently look strongest. Alternative metrics can be useful, but investors should understand exactly how they are calculated and reconcile them with conventional financial statements.
Finally, poor financial controls deserve attention.
Missing statements, inconsistent figures across documents, unexplained transactions, unclear expense classifications, or an inability to reconcile key numbers may indicate that the company has not developed sufficient financial discipline for its current stage.
Questions to ask founders once you’ve reviewed the numbers
The purpose of reviewing startup financials is not simply to calculate ratios but to identify the assumptions that need to be tested directly with the founders.
Start with revenue.
Ask what specifically drove growth during the last several periods. Determine how much came from new customers, expansion within existing accounts, pricing changes, acquisitions, or one-time transactions.
Then ask about retention.
Which customers leave, and why? Has churn changed? Are the company’s strongest customers expanding their spending over time? If management presents retention metrics, ask how they are calculated and which customer groups are included.
Customer acquisition deserves detailed questions as well. How long does it take to recover acquisition costs? Which channels produce the strongest customers? Is acquisition becoming easier or more expensive as the company scales?
Next, discuss spending.
Ask which expense categories would increase first if the company raised additional capital and what measurable milestones that spending is expected to achieve.
Runway should lead naturally into financing questions.
When does management expect to raise again? What milestones does the company need to reach before that round? What happens if the fundraising environment deteriorates or the next round takes six months longer than planned?
Ask about the downside scenario too.
Founders naturally spend much of a pitch explaining what happens if things go well. Investors also need to understand what management would do if revenue came in 20 or 30 percent below plan. Which costs could be reduced? Which investments are contractual commitments? How much additional runway could realistically be created?
Finally, compare the founders’ explanations with the financial statements.
Strong management teams do not need perfect numbers. Early-stage businesses are inherently uncertain, and plans frequently change.
What matters is whether the founders understand their own economics, recognize weaknesses, explain deviations clearly, and make rational decisions when reality differs from the original forecast.
Financial statements cannot tell an investor whether a startup will succeed. They can, however, reveal how the company grows, how efficiently it uses capital, how much risk exists beneath headline revenue, and how much time management has to prove the business model.
That makes a disciplined financial review an essential counterweight to the excitement of the pitch.